

Vested Interest is a bi-weekly newsletter about what the latest developments in economics and finance might mean for your money, career, and life in general.
By submitting your email you agree to Wealthfront’s Terms of Use and will receive newsletter emails at the address provided. You may unsubscribe at any time.
SpaceX is coming for your money and attention
May 29, 2026
 | ||||||||
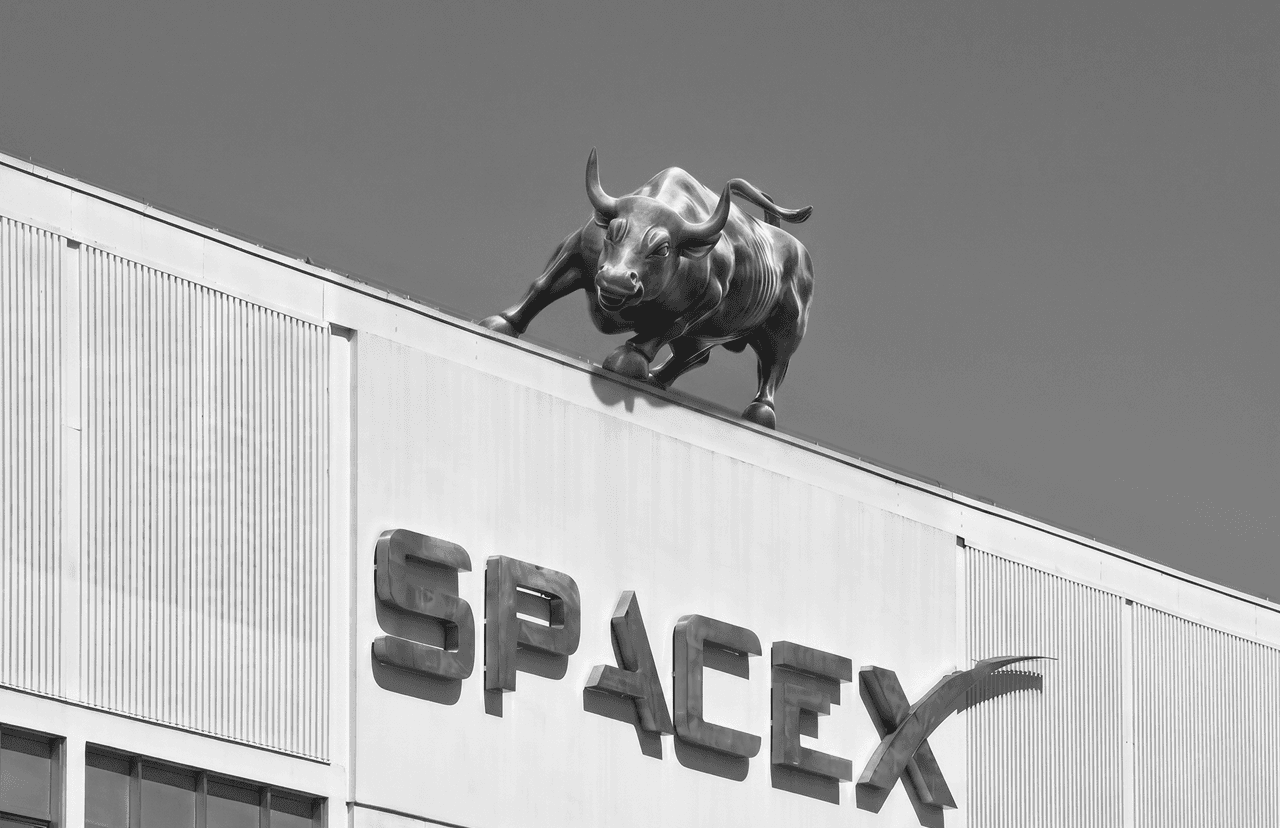 This whimsical composite image of the Wall Street bull statue rampaging across the roof of SpaceX headquarters does not constitute an endorsement of the company’s stock, nor does this disclaimer constitute advice not to buy its stock. Image via Getty and Wealthfront. | ||||||||
 | ||||||||
| Three numbers that explain the economic moment | ||||||||
| ||||||||
| Share this section | ||||||||
 | ||||||||
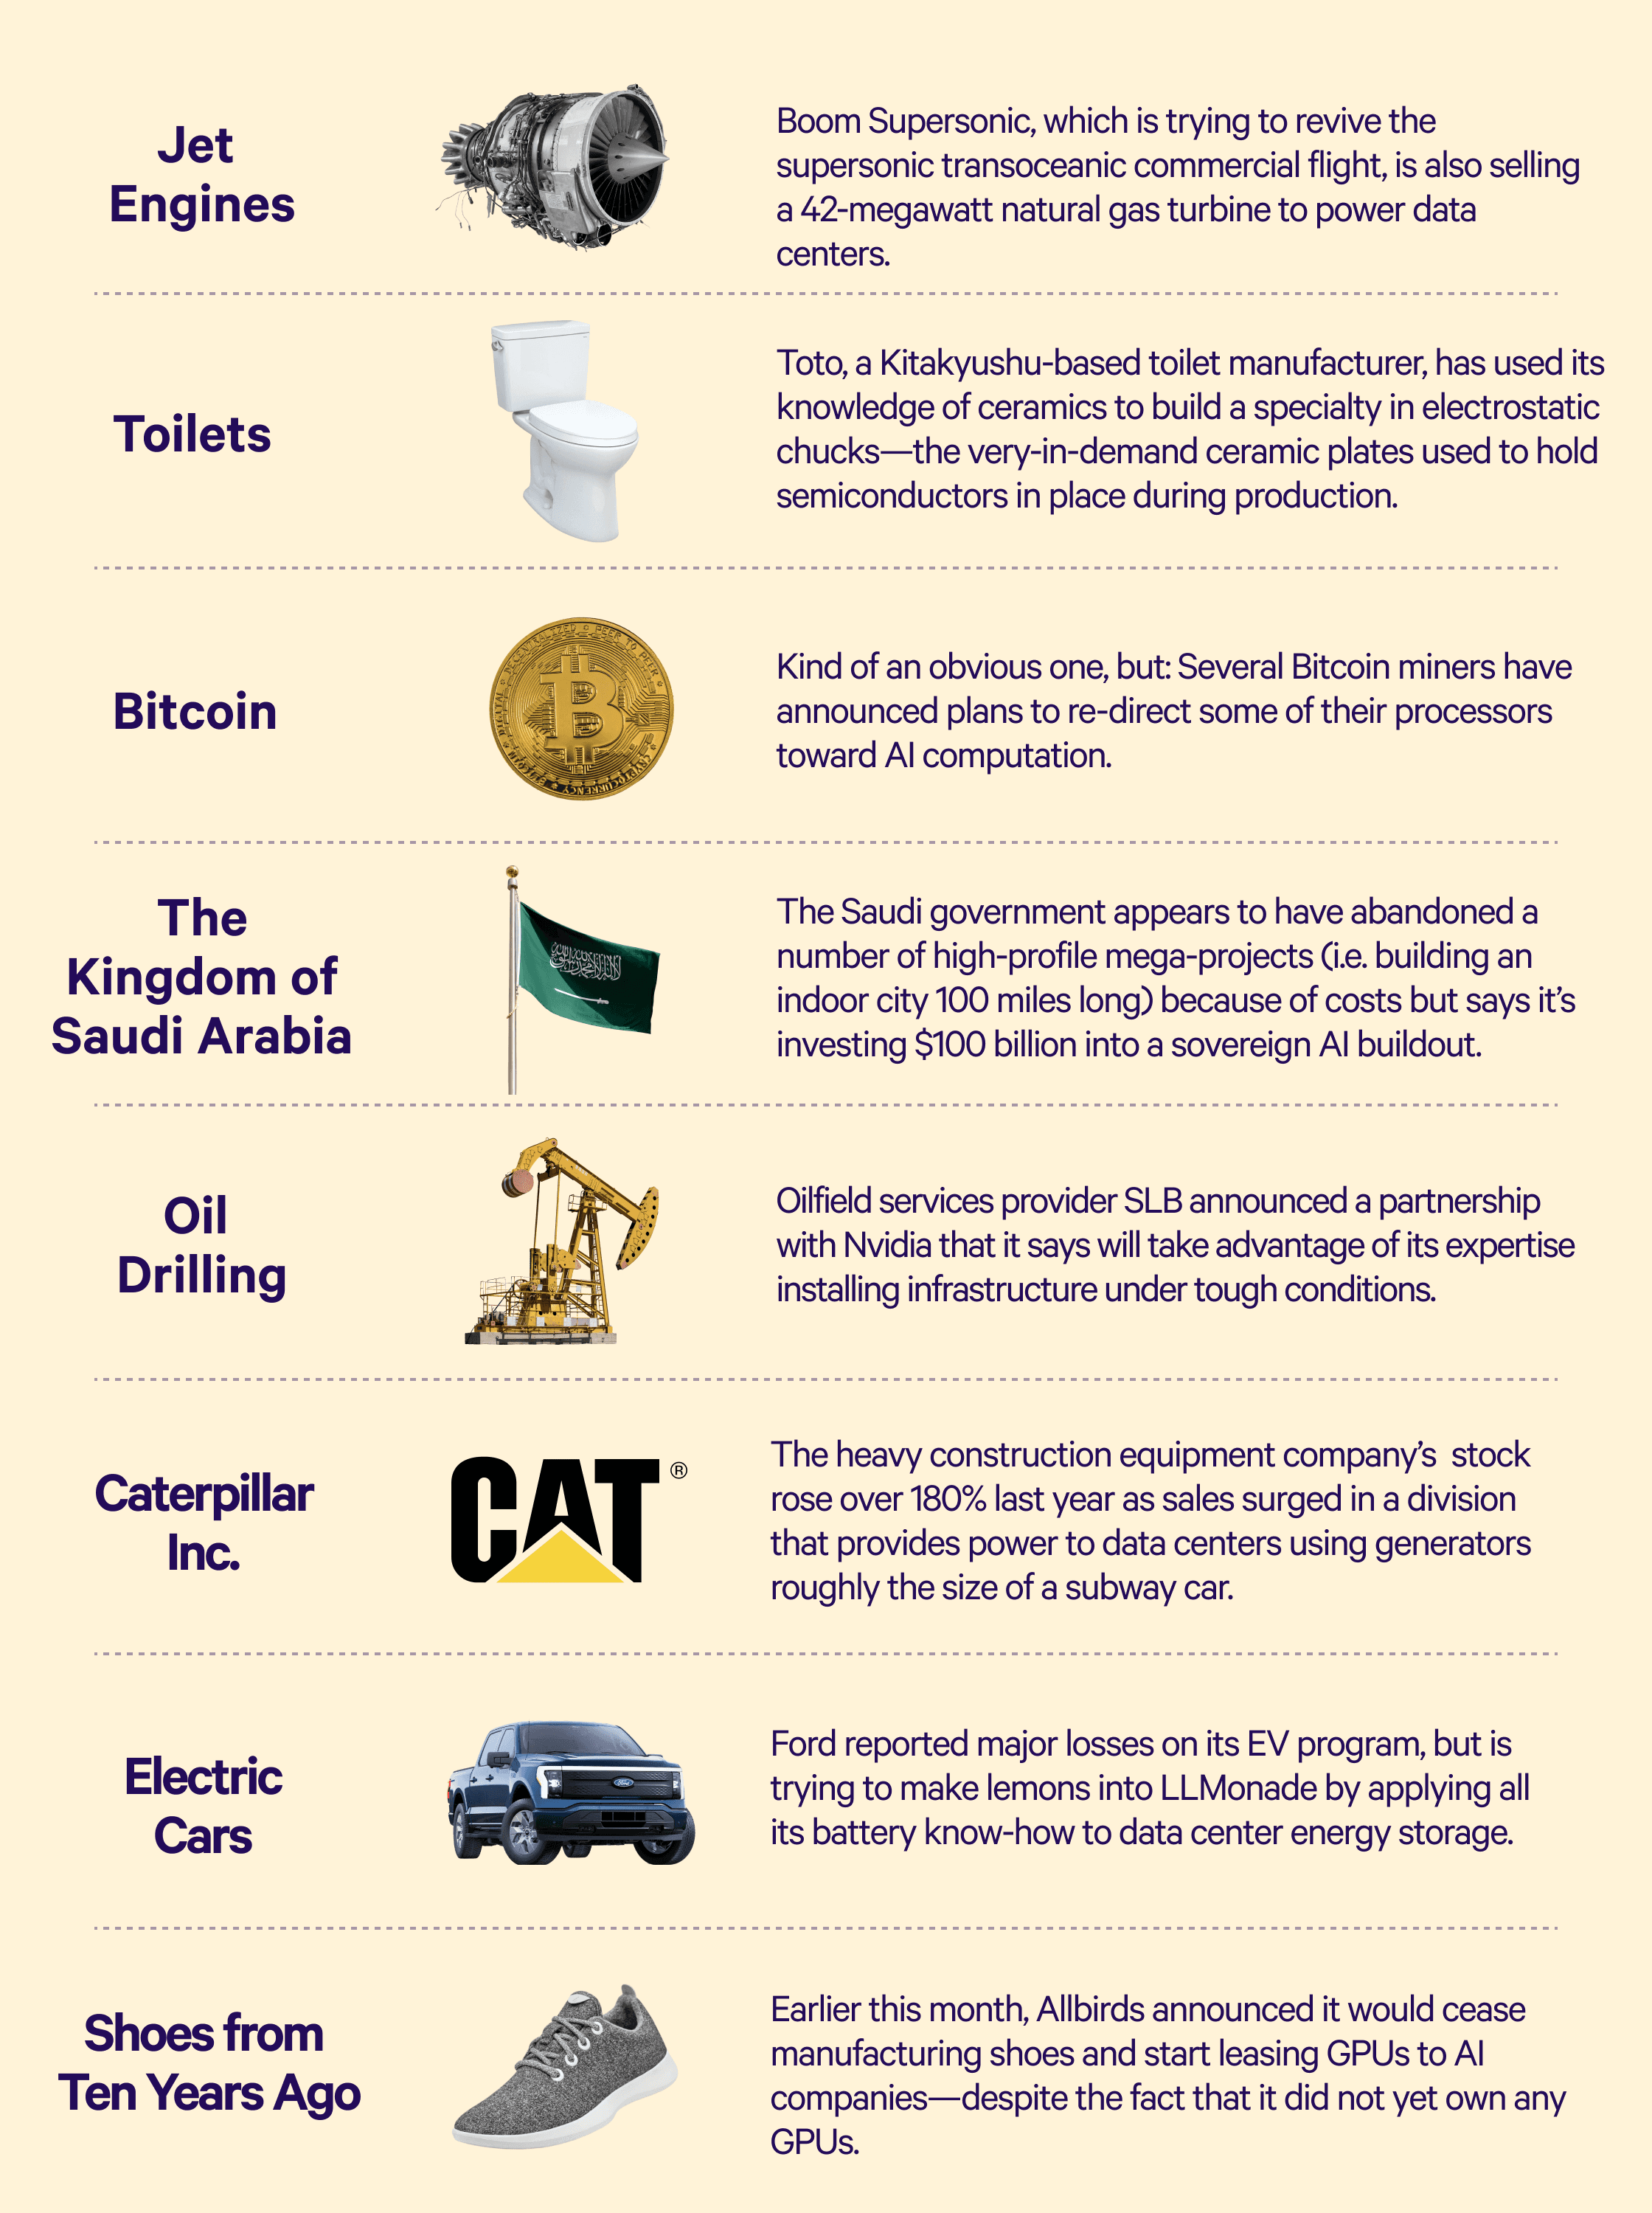
| A running list of things that are AI now | ||||||||
| You can barely turn around without bumping into a new AI “pivot” these days. Here’s our attempt at a comprehensive inventory—and yes, it mentions the Japanese toilets. | ||||||||
 | ||||||||
| Share this chart | ||||||||
 | ||||||||
| Can you answer the hardest question on FINRA’s investor knowledge quiz? | ||||||||
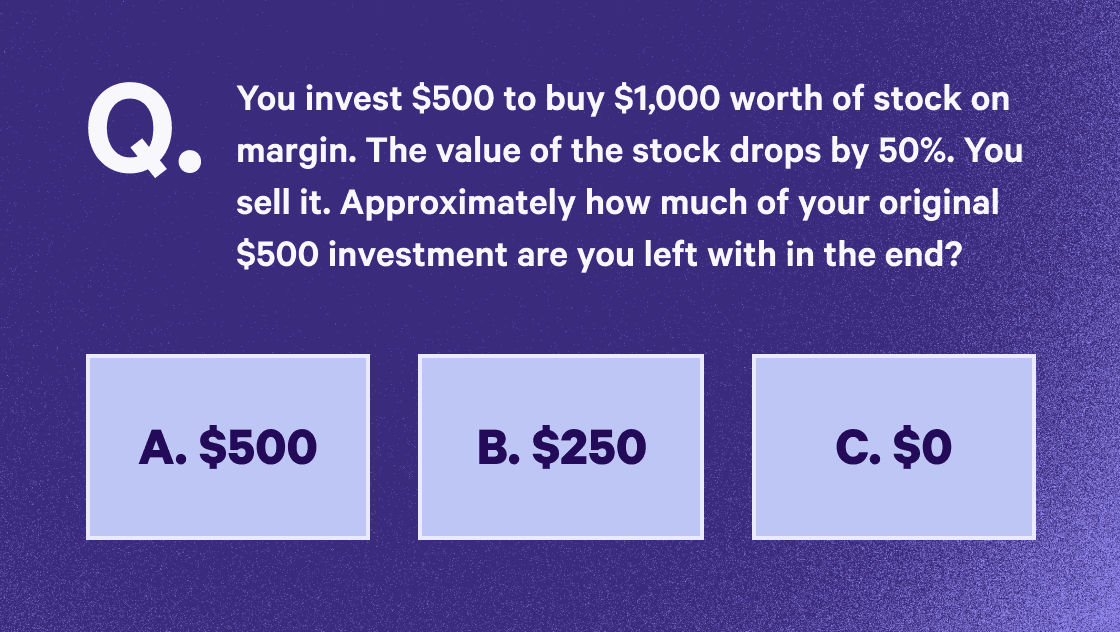 Margin debt in the US is currently at an all-time high. Put another way, this means Americans are borrowing a record amount of money from brokers to fund investing accounts. Concerningly, a question about buying on margin was also the least-correctly-answered item on the Financial Industry Regulatory Authority’s 2025 investor knowledge quiz, which was given to 2,681 Americans who maintain investment accounts separate from their retirement savings. We’ve reproduced the question about margin above; only 20% of the people who took the quiz got it right. See if you can figure it out yourself, then scroll down to see the answer and an explanation of the math. (In the actual quiz, “don’t know” was an option, but we demand more from our readers.) And scroll down a bit more … The correct answer is C, $0. Let’s go through why. 1. “You invest $500 to buy $1,000 worth of stock on margin.” That means you made the purchase by putting some of your own money down and borrowing the rest from your broker. So you’ve now spent $500 of your own money and owe $500 to the broker. And you hold $1,000 worth of stock. 2. “The value of the stock drops by 50%.” The stock that you paid $1,000 for is now worth $500. 3. “You sell it.” Now you have $500 in your pocket. 4. “Approximately how much of your original $500 investment are you left with in the end?” When you sell stock you bought on margin, you have to pay your broker however much you borrowed to buy it originally. Which in this case means you have to give your broker the $500 you just made on your sale. And thus you are left with $0. Stay safe out there! | ||||||||
| Share this section | ||||||||
 | ||||||||
| Your typical “IPOs 101” story wouldn’t quite explain what SpaceX is up to—but this one does! | ||||||||
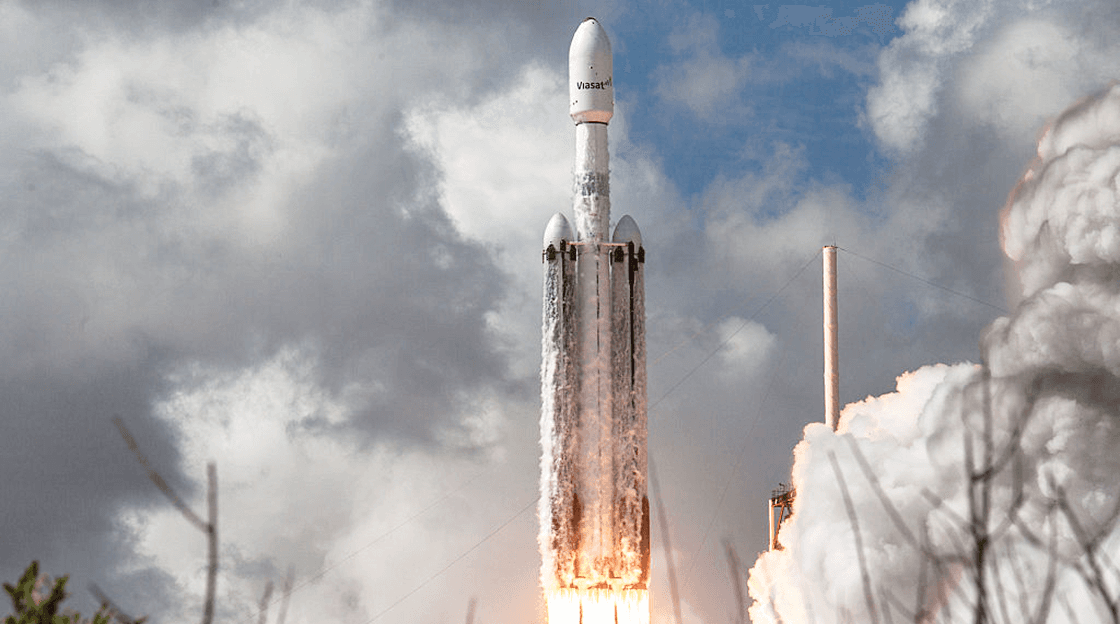 SpaceX’s Falcon Heavy rocket, pictured in the process of taking a satellite into orbit during an April 29 launch at Kennedy Space Center in Florida. Image via Getty. SpaceX, the rockets-and-satellites-and-now-also-artificial-intelligence company controlled by Elon Musk, is targeting June 12 for an initial public offering that’s expected to be the most lucrative ever. With OpenAI and Anthropic looking to follow suit soon, let’s review some of the IPO vernacular that’s going to be getting thrown around in coming months—and discuss why a lot of the assumptions baked into that terminology don’t apply to The Way That We IPO Now (at least if we’re a household-name super-startup attempting to create AGI). To start with, companies (often younger ones) usually make initial public offerings of stock to raise money from the public to fund their operations, make new investments, and generate awareness. In turn, the market provides a reality check on what the company’s private backers—usually a fairly small number of investors—think it’s worth. But SpaceX is already 24 years old and reportedly made about $18 billion in revenue last year, which is more than half the Fortune 500. Some unknown number of individual investors already hold stakes in the company, too, through the hundreds of special purpose vehicles—legal entities that are formed to hold specific assets—that have pooled money to buy chunks of it. “This is not a traditional IPO,” says Aswath Damodaran, a finance professor who studies valuations at New York University’s Stern School of Business. “This is like a public company that’s becoming more public.” One way investors typically estimate how much a private business is worth is by putting its numbers up against those of companies that are already public. Best of luck to anyone trying to find a comparable for SpaceX, though: There aren’t a lot of hybrid rocket-internet-AI-government contractors whose investor relations job listings call for a deep understanding of social media. The company’s goals also make it tough to build a ground-up estimate of how much cash flow it might bring in 5 or 10 years from now; how much revenue do you think a moon base would generate annually? SpaceX isn’t currently profitable—but Musk’s other public company, Tesla, often trades at a premium to its underlying performance. In other words, we’ll learn SpaceX’s price when we see exactly what it trades for after the opening bell on IPO day, but not necessarily its value. “All things in the market are priced,” Damodaran says. “They’re not valued. Price is based on demand and supply.” Musk, for his part, wants the company to go public at a valuation of $1.75 trillion. That aim will guide SpaceX as it determines a free float, which is the number of shares actually up for public sale, and an offer price at which shares will initially be available. (The offer price times the number of total shares that exist in the company, including the ones that are currently private, would need to equal $1.75T.) This is important because typically, a company needs to offer at least 10 percent of its shares to the public in order to gain index inclusion and thus become part of a list like the NASDAQ 100® or S&P 500®. With something like half of the market now estimated to consist of passive investors, who put their money into diversified funds and then leave it alone, that’s a huge amount of potential business on the table. (Once a stock is in the index, index funds have to buy it, pushing its price up.) Previously, indexes have also required companies to be public for a certain amount of time, or to have shown a profit, before including them—but the Nasdaq has already changed its inclusion rules ahead of SpaceX’s IPO in order to fast-track it, and the S&P has been considering tweaking its own to include the company quickly, too. That’s something Damodaran says the indexes more or less have to do to maintain relevance, given how many investors are expected to want exposure to the big stock that everyone’s talking about. (Vested Interest’s position is that maintaining a widely diversified portfolio, rather than trying to forecast the performance of one particular company that may or may not be in an index, has historically been the best way for individual investors to build wealth.) Relevance might be a key concept here. SpaceX is expected to raise less actual money through its IPO than OpenAI did through a private round in March. But it will be signaling its importance in a big way—putting itself top of mind among both index investors and their meme-happy day-trading counterparts, dominating the media, and (if demand for its shares does turn out to be strong) showing off its power and potential to competitors in the AI, tech, and space spaces. The typical IPO involves a roadshow of meetings with investment banks and other institutional heavy hitters; SpaceX will be doing those meetings, too, but they are also taking the case that they matter directly to you. In other words, in its formalities the company’s IPO will look like many others that came before it. But the rest is quintessentially 2026: A behemoth private company that’s already a household name, a polarizing founder with enormous social media clout, and a business plan that aspires to change the very nature of existence. As they say, it’s an attention economy. | ||||||||
| Share this story | ||||||||
 # of mentions of AI in this issue: 9 # of mentions of crypto in this issue: 1 # of mentions of the moon in this issue: 1 |
One new issue, bi-weekly
By submitting your email you agree to Wealthfront’s Terms of Use and will receive newsletter emails at the address provided. You may unsubscribe at any time.